Executive Summary
- Asset protection planning for California business owners works best when implemented proactively.
- Once litigation becomes foreseeable, transfers may be challenged under California’s Uniform Voidable Transactions Act.
- Strong planning often begins with insurance, exemption optimization, disciplined entity maintenance, and layered LLC structures.
- Sophisticated trusts may help in certain situations, but many business owners achieve substantial protection through coordinated legal, tax, and operational planning long before any lawsuit appears.
If you own a business, your biggest asset protection mistake is often waiting until there is a problem.
Many business owners start looking into asset protection strategies only after receiving a demand letter, facing a lawsuit, dealing with a creditor issue, or discovering that a business dispute could threaten personal wealth.
At that point, your options may become limited.
A lawsuit that is already foreseeable can change how courts view asset transfers and restructuring efforts. California’s Uniform Voidable Transactions Act (UVTA) allows courts to examine whether certain transfers were made to avoid creditors or shield assets after a claim became likely.
Effective asset protection for California business owners is built before problems arise. The goal is not to hide assets or avoid legitimate obligations. The goal is to create a legally sound structure that reduces unnecessary exposure, protects business value, and improves your position during disputes.
What Asset Protection Really Means for Business Owners
Many business owners misunderstand asset protection. They assume it means making assets unreachable. That is not realistic.
A proper asset protection strategy focuses on reducing risk before a dispute occurs. It creates legal boundaries between your business activities, personal assets, and potential liabilities.
Effective planning can help you:
- Reduce personal exposure from business risks
- Create a stronger legal separation between assets
- Improve negotiation leverage during disputes
- Protect business continuity
- Reduce the financial impact of unexpected claims
The goal is not to become “judgment proof.” The goal is to make your structure more difficult and expensive to attack. When creditors, plaintiffs, or opposing parties evaluate a claim, strong planning can change the economics of pursuing litigation.
Why Business Owners Should Plan Before Litigation Risks Increase
One of the biggest mistakes business owners make is attempting asset protection planning after a legal threat already exists.
California’s Uniform Voidable Transactions Act gives courts authority to review certain transfers made before or after a creditor’s claim arises. If a transfer appears designed to delay, hinder, or avoid creditors, it may be challenged. Courts often consider factors such as:
|
Factor |
What Courts Review |
|
Timing |
Whether assets were transferred after a claim became foreseeable |
|
Intent |
Whether avoiding creditors was a motivating purpose |
|
Control |
Whether you still control or benefit from transferred assets |
|
Relationships |
Whether transfers involved family members or insiders |
For example, transferring valuable property to a family member after receiving a threat of legal action may create additional legal concerns rather than providing protection.
7 Ways California Business Owners Can Strengthen Asset Protection
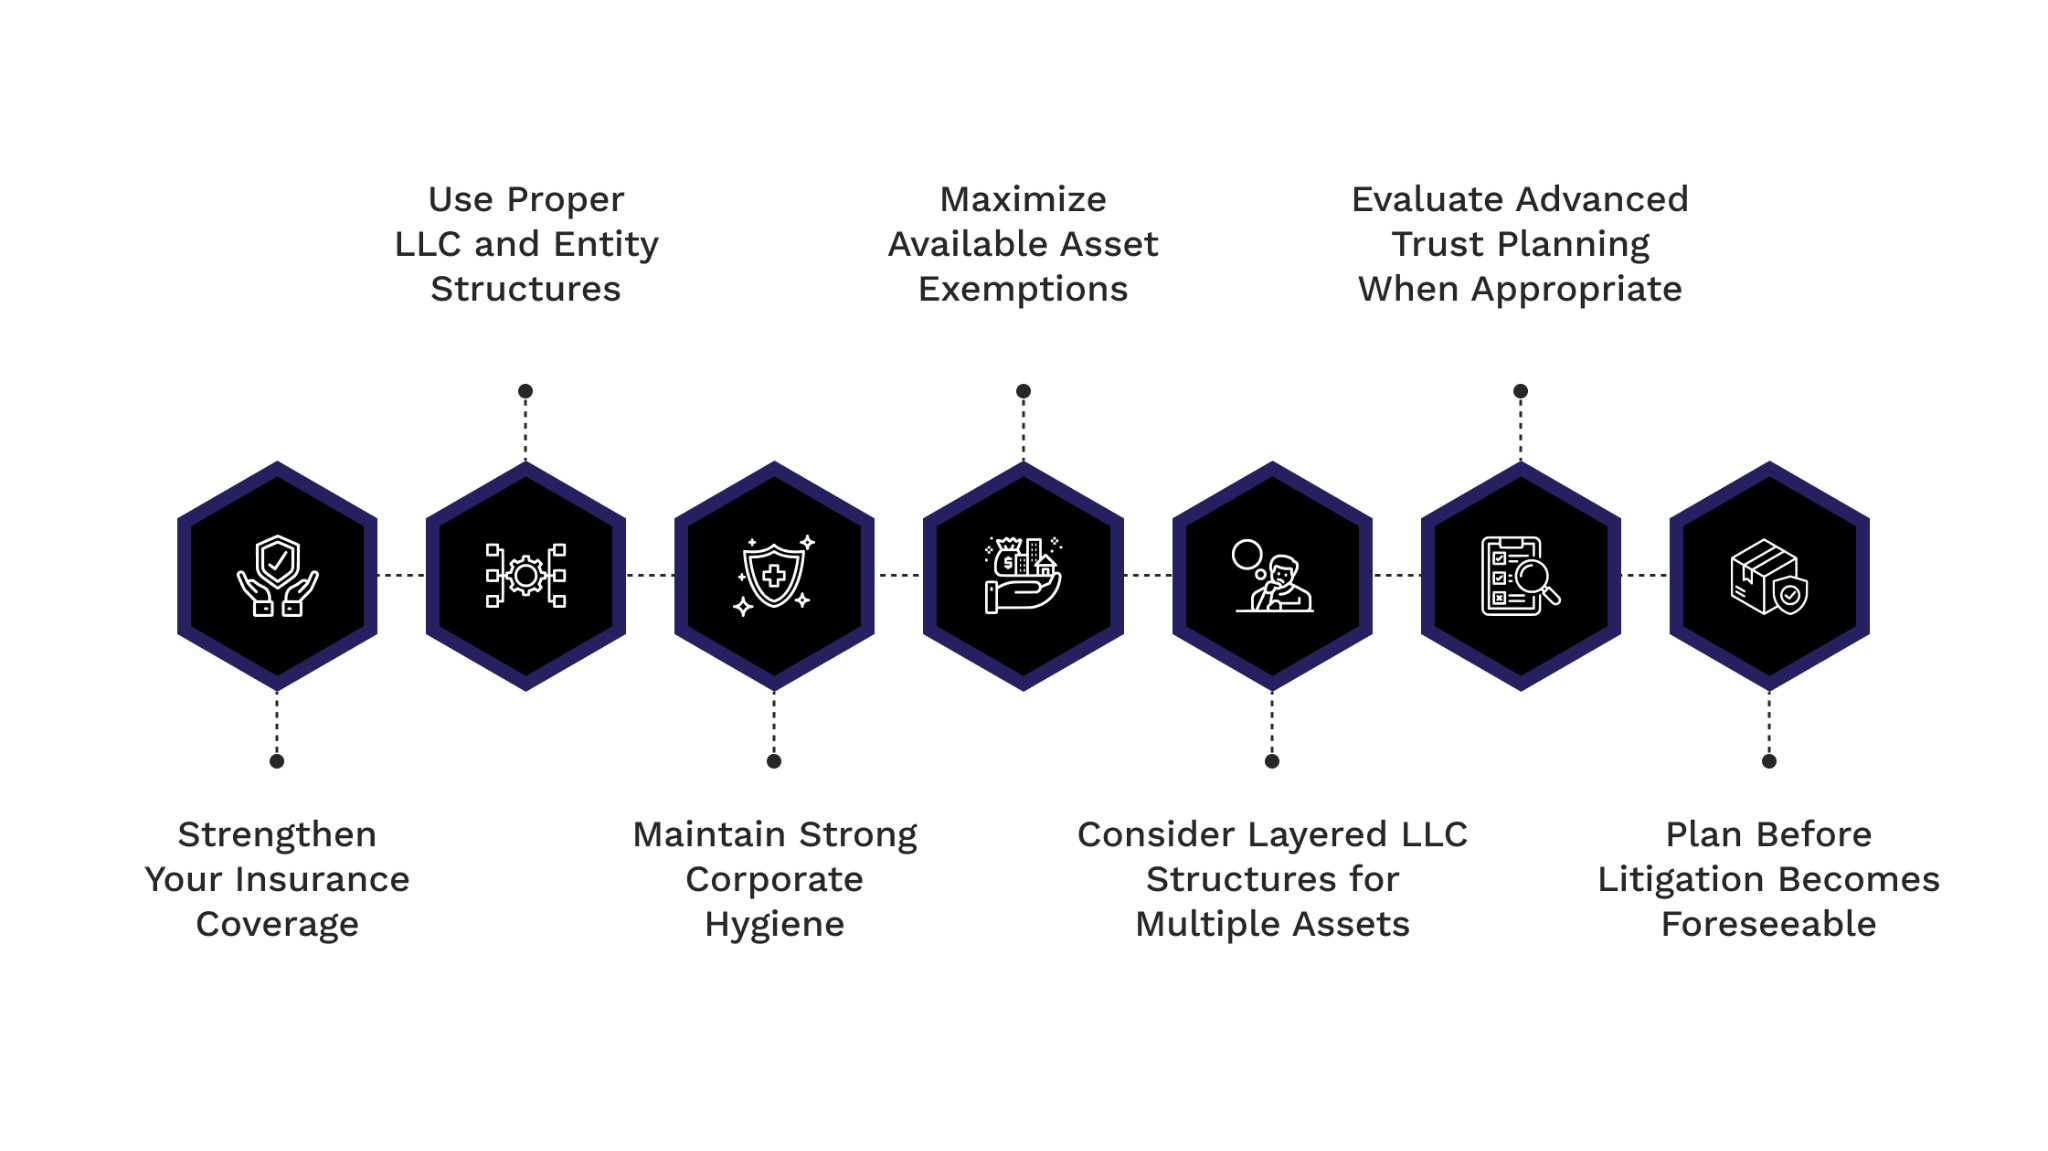
Strengthen Your Insurance Coverage
Insurance is often the first layer of an effective asset protection strategy. Many business owners immediately think about LLCs or trusts when they consider protecting assets. However, insurance provides immediate protection by helping cover legal expenses, settlements, and liability claims.
Without adequate insurance coverage, even well-structured entities may not provide enough protection against significant losses. Review whether your business has appropriate coverage for:
- Commercial general liability
- Professional liability
- Employment-related claims
- Commercial property
- Business vehicles
- Umbrella liability
Umbrella coverage can provide an additional layer of protection above existing policies. However, it usually depends on your underlying policies meeting certain requirements.
As your business grows, your insurance needs can change. A policy that protected you when your company was smaller may no longer provide sufficient coverage after expansion.
Regular insurance reviews should be a key part of your overall asset protection plan.
Use Proper LLC and Entity Structures
Choosing the right business entity is one of the most common components of asset protection for business owners.
An LLC or corporation can create separation between business liabilities and personal assets. However, simply forming an entity is not enough. The protection comes from maintaining the separation between you and the business. A properly maintained asset protection LLC structure requires:
- Separate business and personal accounts
- Signed Operating Agreements and Bylaws
- Share or Membership Certificates
- Written consents or meeting minutes
- Accurate financial records
- Documented business decisions
- Consistent tax reporting
California courts may disregard an entity’s structure when owners fail to respect corporate formalities or treat the company as a personal account. An LLC or a corporation is a valuable tool, but it works only when it is properly structured and maintained.
Maintain Strong Corporate Hygiene
Creating an entity is only the beginning of effective asset protection planning. Many business owners lose valuable protections because they fail to maintain proper business practices. Courts may examine whether you:
- Mixed personal and business funds
- Used company assets for personal expenses
- Failed to maintain records
- Ignored Operating Agreements or Bylaws
- Undercapitalized the business
- Failed to document transactions
- Failed to approve business actions through written consents or meeting minutes
When business and personal activities become mixed, creditors may argue that the entity should not provide protection. Strong corporate hygiene helps preserve the liability protections your business structure was designed to provide.
Maximize Available Asset Exemptions
Certain assets may receive protection from creditors depending on the circumstances. Potentially protected assets may include:
|
Asset |
Considerations |
|
Qualified retirement plans |
Certain ERISA protections may apply |
|
IRAs |
Protection depends on applicable rules and limits |
|
Homestead interests |
|
|
Certain life insurance cash values |
Limited protections may exist |
Exemption planning should be reviewed carefully because protection amounts can vary depending on whether you are dealing with:
- Bankruptcy proceedings
- Civil lawsuits
- Tax collection matters
- Business-related liabilities
Consider Layered LLC Structures for Multiple Assets
Many business owners place multiple properties, investments, or business activities under a single entity. While this may appear simpler, it can create concentration risk.
If one asset or operation creates liability, other assets held in the same entity may become exposed. Layered LLC or corporate structures can help separate different risk areas.
For example:
|
Structure |
Purpose |
|
Parent LLC |
Central ownership structure |
|
Subsidiary LLCs |
Separate ownership of individual businesses/real estate |
|
Operating entities |
Separate, isolated business activities with or without a parent |
A layered approach may help separate liabilities, protect individual assets, improve organizational clarity, and create stronger negotiation leverage
Evaluate Advanced Trust Planning When Appropriate
Trust planning is often discussed as a solution for asset protection. While certain trusts can provide valuable benefits, they are not always the first step.
Some advanced structures include:
- Domestic Asset Protection Trusts (DAPTs)
- Bridge Trusts®
- Private Retirement Trusts
However, many business owners can achieve meaningful protection through foundational planning first. Before considering complex trust structures, evaluate whether you have:
- Appropriate insurance
- Proper entity structures
- Strong financial documentation
- Effective exemption planning
- Clear separation between personal and business assets
Advanced planning tools should support your overall strategy, not replace basic protections.
The right asset protection plan depends on your assets, risks, business structure, and long-term goals.
Plan Before Litigation Becomes Foreseeable
Timing is one of the most important parts of asset protection. California’s Uniform Voidable Transactions Act (UVTA) allows courts to review certain asset transfers made to avoid creditors.
If a transfer occurs after a lawsuit, demand letter, or foreseeable claim appears, courts may question:
- Why the transfer happened
- When it occurred
- Whether you retained control
- Whether the transfer involved insiders
Examples of potentially problematic timing include:
- Moving assets after receiving a legal threat
- Transferring property after a claim arises
- Restructuring ownership after litigation becomes likely
Effective asset protection planning should happen while your business is healthy and before problems appear. The best time to build protection is before you need it.
Build an Asset Protection Strategy That Supports Your Long-Term Goals
Asset protection is not about hiding assets. It is about creating a legal structure that protects your business, your wealth, and your future plans.
Each California business owner faces different risks. Your strategy should reflect your business model, assets, and future objectives.
Dahl Law Group approaches asset protection through its Strategic Planning Counsel for Business Owners™ framework: One Team. One Strategy. Everything Aligned. This means coordinating business entities, tax planning, insurance strategy, succession planning, and long-term wealth protection into a single integrated legal framework rather than addressing each issue separately.
FAQs: Asset Protection Strategies
There is no single solution that works for every business owner. Effective asset protection strategies usually combine insurance coverage, proper entity structures, exemption planning, and disciplined business practices.
Yes, but asset transfers after litigation becomes foreseeable would likely be challenged under California’s Uniform Voidable Transactions Act and be reversed, with costly consequences. Asset protection planning is generally most effective when completed before a claim arises.
LLCs can provide important liability protection, but they must be properly maintained. Mixing personal and business finances or failing to follow LLC formalities can weaken protection.
An asset protection LLC is an LLC structure designed to help separate ownership interests and reduce liability exposure. Its effectiveness depends on proper formation, maintenance, and overall planning.
No, not always. Many business owners benefit from strong insurance, entity planning, and operational discipline before considering advanced trust structures.
Dahl Law Group
Latest posts by Dahl Law Group (see all)
- 7 Asset Protection Strategies California Business Owners Must Consider - August 14, 2026